IKEA’s India market entry strategy combines global standardization with local adaptation. The company adapted its sourcing, pricing, product range, and store experience to meet Indian consumer preferences and regulatory requirements while maintaining its international brand identity.
- Introduction / Executive Summary
When IKEA opened its first large‑format store in Hyderabad on September 26, 2018, the company announced a 30‑year plan to operate 150 stores across India. The launch coincided with a government‑mandated requirement that foreign retailers source at least 30% of their inventory locally. This single regulatory clause forced IKEA to redesign its flat‑pack supply chain, renegotiate vendor contracts, and rethink product sizing for Indian homes.
Within months, the retailer reported that sales were below internal forecasts, prompting a board‑level review of its “India entry” strategy. The case revolves around how IKEA responded to cultural resistance, price sensitivity, and logistical constraints while staying true to its low‑price, high‑design promise.
What Is IKEA’s Company and Industry?
IKEA, the Swedish furniture giant founded in 1943, operates more than 440 stores in 58 markets. Its business model relies on self‑assembly products, standardized designs, and a cost structure that leverages massive economies of scale. The global home‑furnishings market is estimated at $800 billion, with emerging economies contributing a growing share as urban middle classes expand.
India’s retail sector crossed $1 trillion in 2022, driven by a 12% annual urbanization rate and rising disposable incomes among consumers aged 25‑40. However, the market remains fragmented, with a strong presence of unorganized local carpenters and a preference for customized furniture that fits compact, multi‑generational homes.
The Business Challenge
In 2015, IKEA announced its intention to enter India, targeting a market where average household size is 4.8 members and living spaces average 120 sq ft per person. The core challenge was to reconcile IKEA’s global cost‑leadership model with India’s regulatory demand for local sourcing and a consumer base that expects lower price points and culturally resonant designs.
Three intertwined problems emerged:
- Supply‑chain redesign to meet the 30% local content rule without eroding margins.
- Product‑mix adaptation for Indian tastes—smaller sofas, multi‑functional tables, and brighter colour palettes.
- Pricing strategy that could compete with local carpenters who charge 20‑30% less for bespoke pieces.
For official information about IKEA’s products and operations in India, visit the IKEA India website.
Analysis
PESTEL Overview
| Factor | Implication for IKEA |
|---|---|
| Political | Foreign Direct Investment caps; 30% local sourcing rule; state‑level tax incentives for manufacturing hubs. |
| Economic | Rapid middle‑class growth; price elasticity high; currency volatility (INR/USD). |
| Social | Preference for family‑centric, space‑saving furniture; cultural aversion to flat‑pack assembly. |
| Technological | Increasing e‑commerce penetration; mobile‑first payment platforms. |
| Environmental | Government push for sustainable sourcing; IKEA’s own climate‑positive commitments. |
| Legal | Retail licensing restrictions; mandatory local content; labor law complexities. |
Porter’s Five Forces
- Threat of New Entrants: Moderate. High capital requirements deter many global players, but domestic manufacturers can scale quickly.
- Bargaining Power of Suppliers: Low globally, but Indian sourcing mandates elevated the power of local textile and wood suppliers.
- Bargaining Power of Buyers: High. Indian consumers compare IKEA’s flat‑pack prices with handcrafted alternatives.
- Threat of Substitutes: High. Local carpenters, online marketplaces, and informal sellers offer customized solutions.
- Industry Rivalry: Intense. Home‑furnishings brands such as Urban Ladder and Pepperfry compete on design and delivery speed.
SWOT Summary
| Strengths | Weaknesses |
|---|---|
| Globally recognized brand; efficient flat‑pack logistics; deep design expertise. | Rigid product architecture; limited local design talent; higher perceived assembly effort. |
| Opportunities | Threats |
| Untapped tier‑2 cities; growing e‑commerce logistics network; government incentives for manufacturing. | Regulatory changes; price wars with local artisans; cultural resistance to DIY assembly. |
Value Chain Adjustments
IKEA re‑engineered three key nodes:
- Inbound Logistics: Established two regional sourcing hubs in Tamil Nadu and Gujarat to meet the 30% rule.
- Operations: Introduced a “Made‑in‑India” product line with reduced dimensions and locally sourced hardwoods.
- Outbound Logistics: Partnered with Indian third‑party logistics firms to handle last‑mile delivery in congested metros.
Strategic Options Considered
Before committing to the Hyderabad rollout, IKEA evaluated three pathways:
- Full‑Scale Replication: Duplicate the European store format, rely on imports, and absorb higher duties. This would preserve brand consistency but breach the local‑content law.
- Joint‑Venture with an Indian Manufacturer: Share risk, leverage local design expertise, and meet sourcing requirements. However, control over quality and brand experience could dilute.
- Gradual Market Penetration via Pop‑Up Stores: Test product acceptance in Tier‑2 cities with temporary locations, gather consumer insights, and scale only successful SKUs.
What the Company Actually Did / Outcome
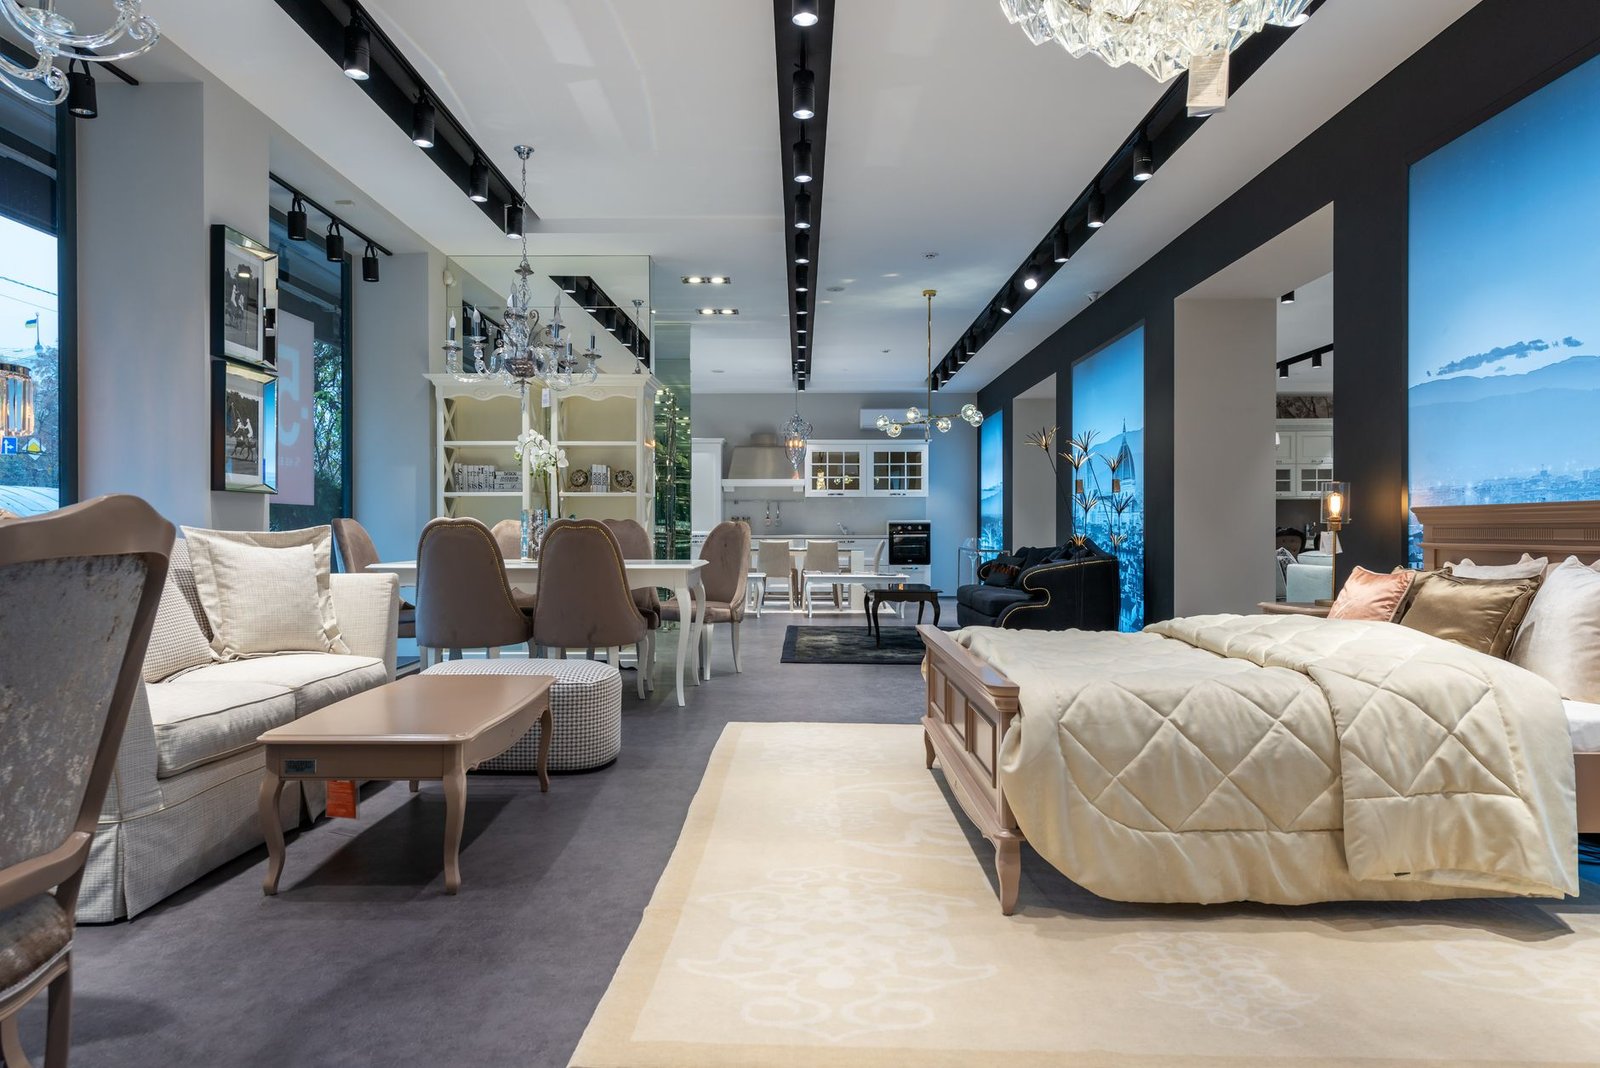
IKEA chose a hybrid approach: it built a 140,000 sq ft flagship in Hyderabad, sourced 30% of its inventory from Indian suppliers, and launched a localized “IKEA India” catalogue featuring smaller sofas, modular kitchen units, and bright‑hued textiles. The company also opened a design studio in Bengaluru to co‑create products with local artisans.
Initial sales lagged by 15% compared with projections, prompting a price‑adjustment campaign that introduced a “Flat‑Pack ₹1999” range targeting price‑sensitive shoppers. Within two years, the Hyderabad store achieved break‑even, and IKEA announced plans for additional stores in Mumbai, Delhi, and Bengaluru, each with a higher proportion of locally manufactured goods.
Key outcomes include:
- Local sourcing grew from 30% in 2018 to 45% by 2023, improving margin stability.
- Customer satisfaction scores rose 12 points after the introduction of assembly‑assist services.
- IKEA’s brand perception shifted from “foreign luxury” to “affordable Indian‑style home solutions.”
Key Takeaways for MBA Students
- Regulatory constraints can become a catalyst for supply‑chain innovation rather than a mere compliance cost.
- Adapting product dimensions and design language to local living conditions is essential for consumer acceptance.
- Hybrid entry modes—combining wholly‑owned stores with local partnerships—balance control with market responsiveness.
- Pricing elasticity in emerging markets may require a dedicated low‑price sub‑range to compete with informal sellers.
- Continuous feedback loops (e.g., design studios, pop‑up tests) reduce the risk of large‑scale mis‑fit.
Discussion Questions
- How could IKEA have better aligned its global cost‑leadership model with India’s 30% local‑content rule without sacrificing profitability?
- What are the trade‑offs between maintaining a standardized brand experience and customizing product designs for cultural relevance?
- If you were the CFO, which financial metrics would you prioritize to evaluate the success of IKEA’s India expansion?
- Would a joint‑venture with a major Indian furniture manufacturer have accelerated market acceptance, or would it have diluted IKEA’s brand equity?
This case study is for educational discussion only, synthesizes publicly available information, and should be cross‑checked against primary sources before academic citation.